
Later Life Lending: From Retirement Mortgages to Equity Release
Later life lending is about looking at mortgage and borrowing options for people later in life. Understanding what may be available can help you make a more informed decision about your home, your finances and your future.
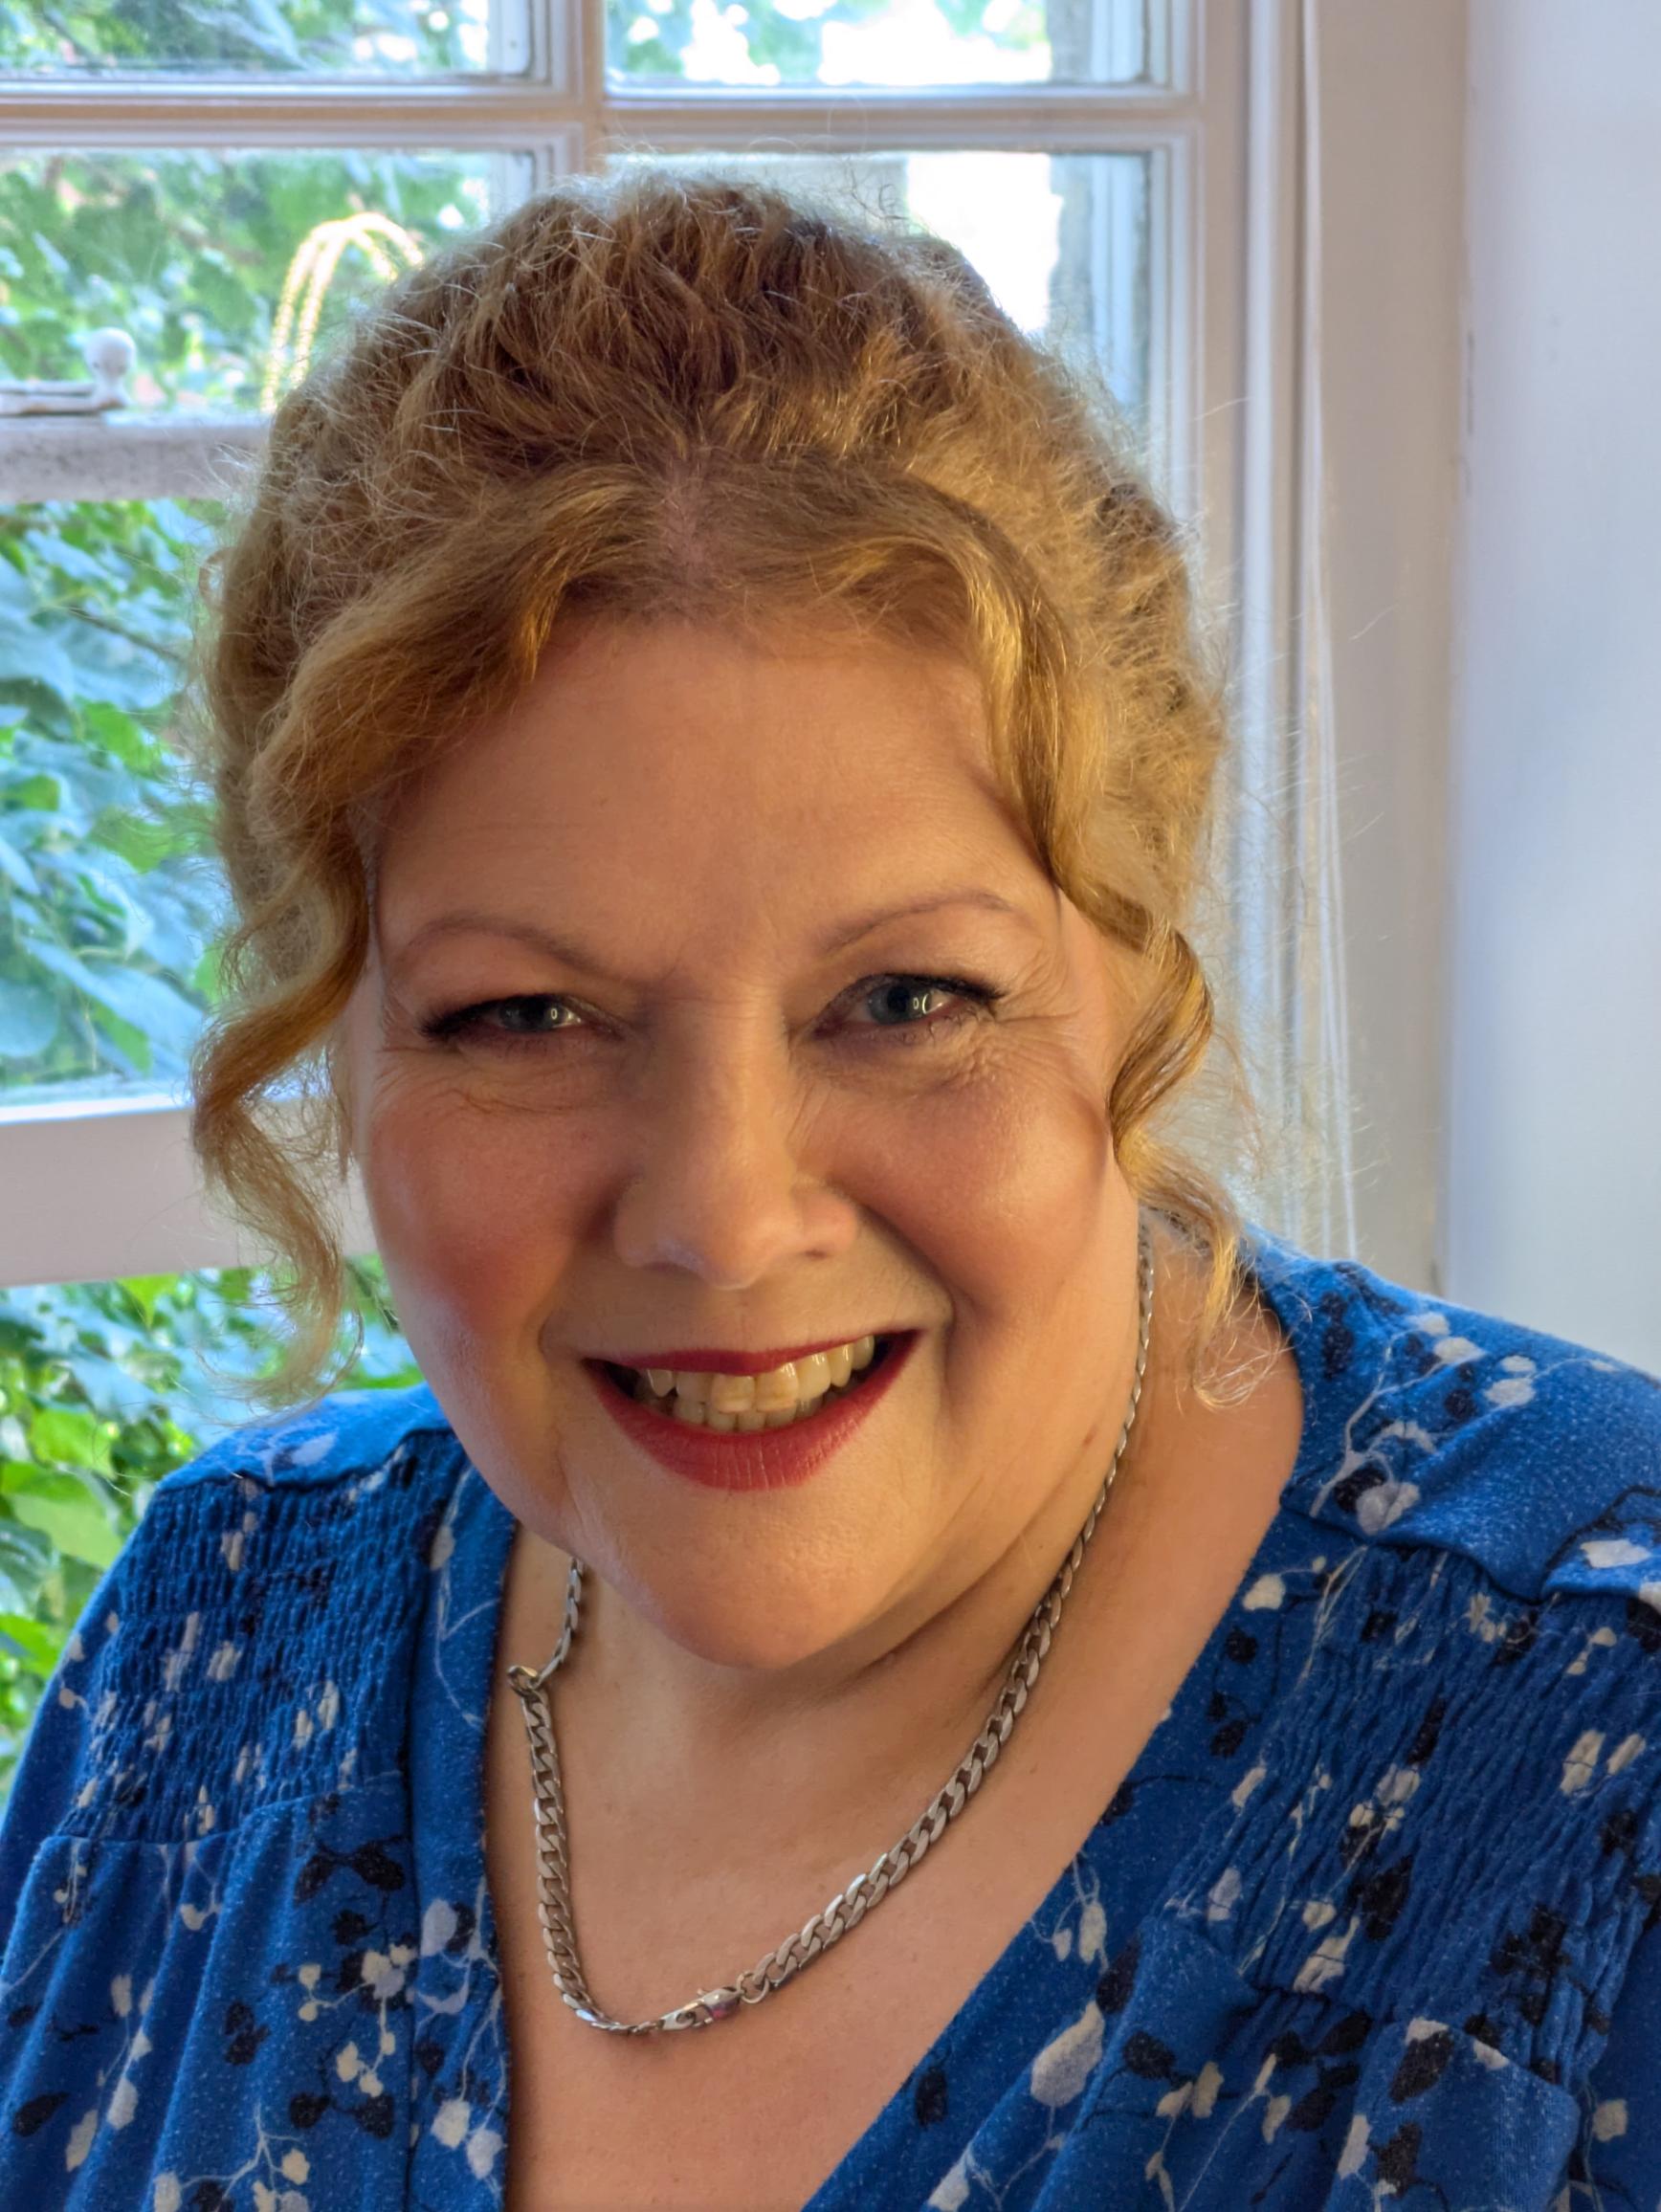
Janet Hardy is a Later Life Lending Specialist in Swindon and the surrounding area. As a Later Life Accredited Adviser, she has experience helping clients explore later life lending options, including lifetime mortgages and equity release.
Later life lending can sound complicated at first, but the basic idea is simple. It is about looking at mortgage and borrowing options that may be available later in life.
That might be because you want to stay in your home, support family, make home improvements or because your current mortgage situation is changing.
There is no one-size-fits-all answer, which is why careful advice is important.
Later Life Lending
Meet Janet Hardy
Later Life Lending Specialist in Swindon
Janet helps clients understand their mortgage and borrowing options later in life, including lifetime mortgages and equity release.
Every situation is different, so Janet takes the time to understand what clients are trying to achieve and explain the options that may be available.
Meet JanetWhat can later life lending involve?
Later life lending can cover different types of borrowing.
For some people, it may mean looking at a mortgage that runs into later life. For others, it may mean considering equity release or a lifetime mortgage.
It may also involve reviewing an existing interest-only mortgage or looking at options if a current mortgage term is coming to an end.
The right route can depend on your income, age, property and what you want the borrowing to achieve.
Some people want to make their home more comfortable or adapt it for future needs. Others want to help children or grandchildren, manage existing borrowing or simply understand their options.
Later life lending is a regulated area that needs careful consideration before any decision is made.
Can you get a mortgage in retirement?
“I’m retired. Can I still get a mortgage?”
It’s a question that comes up quite often.
Being retired does not automatically mean borrowing is impossible. But there is no blanket answer either.
Lenders have their own criteria and may consider your income, affordability, age, the property and the proposed mortgage term.
It is important not to assume:
“I’m this age, so I definitely can.”
Or:
“I’m this age, so I definitely can’t.”
That is not how later life lending should be approached. The starting point should be understanding your circumstances and plans.
What about pension income?
Income is often one of the big questions when considering a mortgage in retirement.
When you are retired, your income may look very different from when you were working. You might have pension income, investment income or other sources of regular income.
Different lenders can have different criteria and may treat different types of income in different ways.
So don’t assume that because you no longer receive a salary, there is nothing for a lender to consider. Equally, don’t assume every type of income will automatically be treated in the same way.
Affordability remains important. The value of your property does not automatically determine how much you can borrow or what may be suitable for you.
What is a lifetime mortgage?
A lifetime mortgage is one option that may be considered as part of later life lending. It is a type of equity release mortgage secured against your home. Usually, the loan and any interest are repaid when the last remaining borrower dies or permanently moves into long-term care.
If you are considering one, it is important to understand how it works, including its features, costs and longer-term implications.
Depending on the option being considered, there may be different ways of accessing funds. This can include taking a lump sum or, where available and appropriate, using a drawdown lifetime mortgage to access funds in stages.
The starting point should be what you are trying to achieve rather than a particular product.
Releasing equity from your home
“I have a lot of equity in my home.”
“Should I release some of it?”
It’s a question that comes up quite regularly.
One important question to ask is:
“Why?”
Not because there’s necessarily anything wrong with releasing equity, but because why you are considering it can be really important.
Your home may be one of your biggest assets, so borrowing against it deserves careful consideration.
What could you use the money for?
Maybe you want to make improvements to your home. Perhaps you are helping a family member. You may be looking at managing existing borrowing, or have another reason entirely.
There is not necessarily a right or wrong answer.
But understanding the purpose behind the borrowing is important. Depending on your circumstances, there may also be different ways of achieving what you are trying to do.
So don’t start with the product. Start with the problem you are trying to solve.
What are the wider implications?
Depending on the option you are considering, there could be interest, fees and other costs.
The longer-term cost of borrowing is important, not just the amount you receive at the beginning.
Your future plans matter too.
If leaving an inheritance is important to you, additional borrowing could affect the amount of equity available in your property later on.
Some later life lending options may also have implications for means-tested benefits.
That does not automatically mean borrowing is inappropriate. It means these factors should form part of the decision.
Releasing equity should never be reduced to one headline figure. A number does not tell your story. Your circumstances do.
Looking at the bigger picture
When considering borrowing later in life, there are some important questions to ask.
- Do you want to stay in your home long term?
- Are you planning to move later on?
- Do you want to leave an inheritance?
- Do you want to reduce monthly payments?
- Do you need access to funds for a specific reason?
It can also be helpful to talk things through with family where appropriate, as later life lending decisions can affect more than just the person applying.
Sometimes the right answer is no
Sometimes the right answer is no.
Sometimes it might be borrowing less. Another option may be more appropriate. And sometimes doing nothing at all could be the right decision.
Good later life lending advice is not about finding a reason to borrow. It is about understanding what you are trying to achieve, explaining the options that may be available and helping you understand the potential implications.
This is your home. It’s your money. And ultimately, it’s your decision.
Later life lending advice in Swindon
If you are considering later life lending in Swindon, you do not need to arrive with a decision already made.
Whether you are approaching retirement, already retired, reviewing an existing mortgage, considering a lifetime mortgage or wondering whether releasing equity could help you achieve a particular goal, the first step can simply be understanding your options.
As a Later Life Lending Specialist in Swindon, Janet Hardy can help you look at your circumstances calmly and clearly and understand what may be available.
There is no pressure to choose an option before you are ready.
If later life lending is something you are considering, get in touch and the options can be talked through.
Frequently asked questions about later life lending
Can I get a mortgage if I am retired?
Being retired does not automatically mean you cannot get a mortgage. Lenders have their own criteria and may consider your income, affordability, age, property and proposed mortgage term.
Can pension income be used for a mortgage?
Pension income may be considered by a lender, but different lenders can have different criteria for different types of income.
What is later life lending?
Later life lending is a broad term covering mortgage and borrowing options for people later in life. This can include mortgages that run into retirement, reviewing existing borrowing, lifetime mortgages and equity release, depending on individual circumstances.
What is a lifetime mortgage?
A lifetime mortgage is one form of later life borrowing. If you are considering one, it is important to understand its features, costs and risks and how it could fit with your plans.
What is a drawdown lifetime mortgage?
A drawdown lifetime mortgage is a type of lifetime mortgage where funds may be accessed in stages rather than necessarily taking the full amount at the outset. Availability and suitability depend on your circumstances and the relevant product criteria.
Should I release equity from my home?
There is no one-size-fits-all answer. It is important to understand why you want to access the money and consider whether there are other ways of achieving what you are trying to do.
Can equity release affect inheritance?
It can. Additional borrowing may affect the amount of equity available in your property later on, so inheritance plans should form part of the wider conversation.
Can equity release affect means-tested benefits?
It may. Releasing money from your home can affect entitlement to means-tested benefits, so this should be considered before making a decision.
Considering your options?
You do not have to work out your later life lending options alone.
If you want to understand what may be available, get in touch with Janet Hardy, Later Life Lending Specialist in Swindon.
Start with a conversation. Understand your options. Then decide what is right for you.
Important: Mortgages and later life lending are subject to lender criteria and individual circumstances. Equity release is a complex area and can affect your estate and entitlement to means-tested benefits. Your home may be repossessed if you do not keep up repayments on your mortgage. Fees and other costs may apply. You should consider whether the advice you receive is suitable for your circumstances before proceeding.